Market overview and industry significance of the Flare Monitoring Market
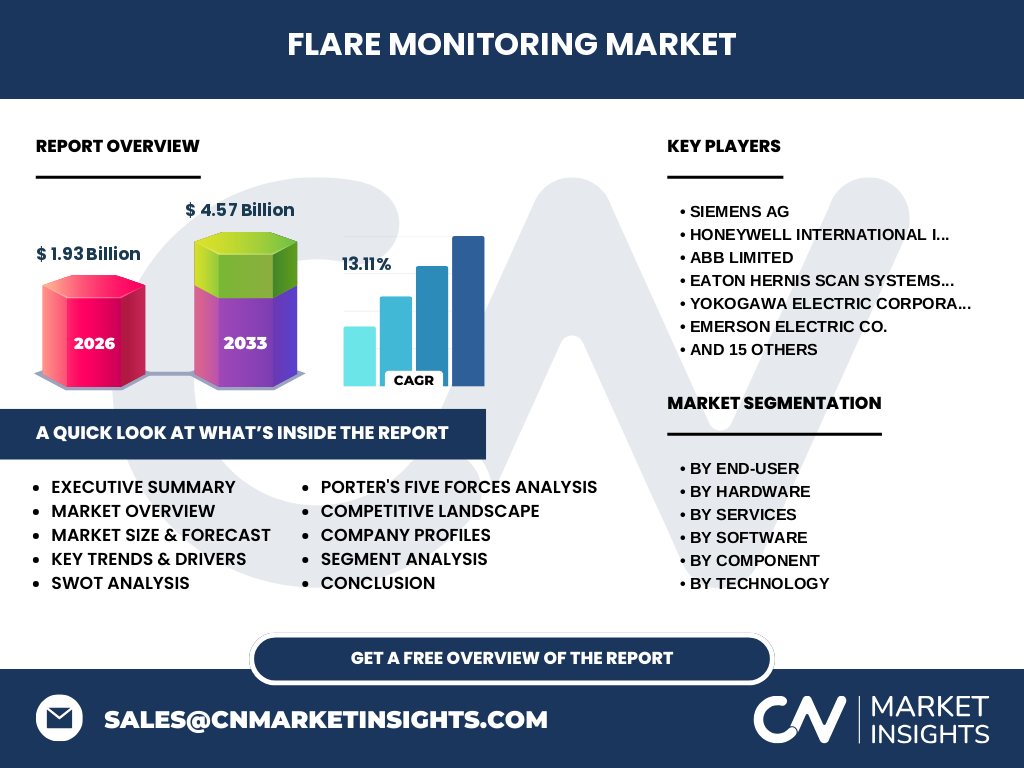
The Flare Monitoring Market is a mission-critical segment for global energy infrastructure, valued at $1.93 Billion in 2026. It encompasses the systems required to detect, measure, and report flare stack emissions. As energy majors face increasing scrutiny from agencies like the EPA and EU regulatory bodies, these systems are vital for maintaining operational compliance and reducing methane intensity in downstream refineries and upstream extraction sites.
Structural Growth Drivers, Restraints, and Opportunities
Primary growth is fueled by stringent environmental mandates forcing accurate emission quantification. However, high capital expenditure for retrofitting aging infrastructure acts as a restraint. Our research indicates massive opportunities for predictive analytics to minimize waste. The shift toward sustainable energy practices necessitates advanced sensor integration, positioning firms that provide automated, real-time reporting as the industry leaders within this evolving landscape.
Emerging trends and growth patterns in Flare Monitoring Market
The market is witnessing a decisive shift toward automated emission quantification and cloud-based data management. We observe a strong trend where optical and infrared monitoring technologies are replacing traditional, manual estimation methods. Companies focusing on predictive analytics and fault detection software are capturing significant market share as operators strive to optimize combustion efficiency and proactively address potential safety breaches at high-pressure gas facilities.
COVID-19 impact analysis and recovery trajectory
The pandemic caused initial disruptions due to global supply chain bottlenecks and labor shortages, temporarily stalling refinery maintenance cycles. However, the recovery trajectory has been robust, driven by post-pandemic ESG commitments. The market saw a resurgence as digitalization efforts accelerated, with companies like Siemens AG and Honeywell International Inc. pivoting to remote monitoring solutions that bypass site-access limitations during high-volatility periods.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is highly concentrated, with dominant incumbents such as ABB Limited, Emerson Electric Co., and Yokogawa Electric Corporation setting the standard for hardware precision. Competitive dynamics are shifting as specialized firms like Fluenta AS and Zeeco Inc. innovate in ultrasonic flow metering. Success now relies on providing a holistic stack, integrating hardware precision with sophisticated compliance management software to simplify regulatory reporting for clients.
Executive summary of key findings
The Flare Monitoring Market is poised for exponential expansion, projected to reach $4.57 Billion by 2033 at a CAGR of 13.11%. Our research underscores that environmental regulatory compliance is the primary economic engine for this sector. Strategic investment in cloud-based data management platforms and high-fidelity sensors remains the most effective path for vendors to maintain competitive differentiation in a rapidly digitizing oil and gas market.
Market forecast from 2027 to 2033
We anticipate a steady acceleration in revenue, starting from a robust baseline in 2026. The projected growth to $4.57 Billion by 2033 suggests that the market will more than double within this seven-year window. This trajectory is supported by the increasing adoption of advanced infrared monitoring across North American and Middle Eastern production sites, as operators race to comply with global net-zero emission targets.
Segmentation analysis by technology and end-use
Segmentation is categorized by hardware, software, and services, with Oil and Gas remaining the dominant end-user. Optical and Infrared Cameras are gaining traction due to their ability to detect non-visible gas leaks. Meanwhile, Compliance and Regulatory Management Software represents the highest growth sub-segment, as industrial players prioritize digital accountability to avoid heavy fines from agencies monitoring fugitive emission volumes and combustion efficiency.
Regional market analysis and performance trends
North America continues to lead in market adoption, driven by strict EPA methane regulations. Conversely, the Middle East is rapidly scaling its infrastructure, with a growing reliance on ultrasonic monitoring to optimize massive petrochemical outputs. Europe is witnessing significant integration of remote monitoring and managed services, as regional carbon pricing mechanisms incentivize companies to minimize flare events through advanced technological oversight and predictive maintenance schedules.
In-depth regional review: North America vs. Asia-Pacific
North America remains the epicenter of innovation, heavily influenced by shale gas production dynamics and leak detection and repair (LDAR) mandates. Meanwhile, the Asia-Pacific region displays high potential for growth, supported by massive investment in petrochemical refining. While North American markets favor highly integrated, software-defined solutions, the Asia-Pacific region is currently scaling its foundational hardware-based flare detection footprint to match rising industrial production output.
Company profiles and strategic positioning
Leading entities like Thermo Fisher Scientific Inc. and AMETEK Inc. focus on high-precision analytical sensors, catering to the exacting needs of refineries. Teledyne FLIR LLC leverages its infrared expertise to dominate the optical monitoring space. Meanwhile, KROHNE Group and Fluenta AS emphasize flow metering precision. Each player is strategically positioning itself as a total solutions provider to capture greater wallet share within the lucrative maintenance and service contracts.
Porter's Five Forces assessment
The threat of new entrants is moderate due to high R&D hurdles and strict certification requirements. Bargaining power of buyers is high, given that energy majors often dictate strict compliance parameters. However, supplier power is limited, as the industry relies on a specialized, high-tier sensor market. Rivalry among incumbents—including Eaton Hernis Scan Systems AS and VisionTIR S.L.—remains fierce, centered on technological superiority and long-term service agreements.
SWOT Analysis: Strategic Outlook
The market's Strengths lie in the essential nature of emission reporting. Weaknesses include the legacy hardware integration complexity. Opportunities are abundant in Predictive Analytics and Fault Detection Software, allowing for proactive incident prevention. Conversely, Threats stem from volatile energy prices and the potential shift toward renewable energy sources, which may reduce the total number of long-term flare monitoring points if legacy assets are decommissioned too rapidly.
Value chain analysis from raw materials to end-users
The value chain originates from specialized semiconductor and sensor component manufacturers. These materials flow to system integrators like Emerson Electric Co. or Siemens AG, who assemble integrated hardware/software packages. These are then deployed at onshore and offshore production sites. The final value is realized through consulting and regulatory compliance services, where firms verify data integrity for environmental agencies, closing the loop between industrial operation and regulatory transparency.
Investment insights and high-potential areas
Investors should prioritize companies demonstrating a shift toward Software-as-a-Service (SaaS) business models, specifically in emission quantification and reporting. The integration of Cloud-Based Data Management Platforms with edge-computing hardware offers high-margin scalability. Areas like Offshore Oil And Gas Production Sites represent high-barrier-to-entry segments, favoring established players with the technical infrastructure to provide reliable, remote-managed monitoring services in challenging, corrosive, and high-pressure offshore environments.
Conclusion and key takeaways
The Flare Monitoring Market is essential to the future of the global energy sector, driven by a CAGR of 13.11%. Key takeaways include the inevitability of digital transformation and the rising necessity for regulatory compliance automation. As the market moves toward $4.57 Billion by 2033, successful participants will be those who seamlessly combine precise ultrasonic/infrared hardware with intelligent data platforms to turn emissions reporting into operational efficiency.
Research methodology: How baseline estimates are triangulated
Our research methodology relies on triangulation between trade registry data, primary stakeholder interviews, and macroeconomic indicators. We cross-reference official filings from major players like Yokogawa Electric Corporation with regional environmental agency reports. This bottom-up aggregation, verified by industry expert panels, ensures that our $1.93 Billion market size and 2033 forecasts reflect actual industrial procurement cycles and verified regulatory spending across key international markets.
Scope of the report: Coverage parameters and limitations
This report covers the global Flare Monitoring Market, including Hardware, Software, and Services across all major applications. It examines market dynamics in North America, Europe, Asia-Pacific, and the Middle East. While providing granular insights into predictive analytics and flame ionization detection, the scope excludes small-scale laboratory-grade flare applications, focusing strictly on industrial-scale Oil and Gas, Petrochemical, and Chemical plant infrastructure requirements and their associated global compliance needs.
Recent developments in the market
Major strategic moves, such as partnerships between software developers and traditional sensor manufacturers, highlight a trend toward unified platforms. Recent announcements from companies like Sensia Solutions S.L. regarding AI-driven flare event detection indicate a rapid shift toward machine learning. These product launches and strategic alliances are focused on reducing false positives, thereby increasing the reliability of compliance reporting and helping operators avoid costly penalties in an increasingly monitored global environment.